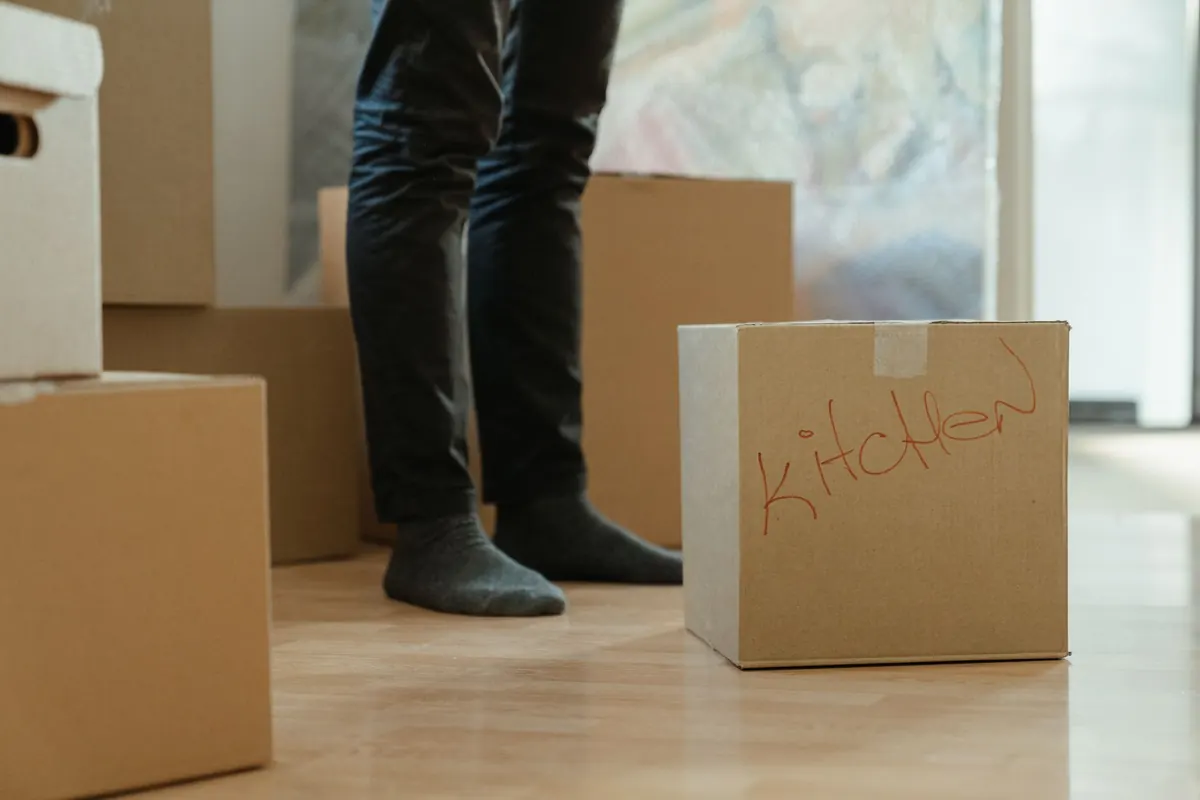
Every move hides two budgets. The first is loud and obvious: the truck, the boxes, the deposit, the pizza you buy for the friends who carry a couch down three flights of stairs. The second is quieter and usually bigger — rent, heat, car insurance, the bus pass, the grocery bill in a city whose prices you don't know yet. Most people plan the first one carefully and get ambushed by the second. Here's a way to plan both, using the specific numbers for the place you're actually going, not a national average.
Rent is the headline, but it's rarely the whole story. Two cities with identical rents can feel several hundred dollars a month apart once you add commuting, insurance, utilities, and taxes. Build a simple side-by-side grid — one column for where you live now, one for where you're headed:
A cheaper apartment forty minutes further out can cost more than the rent you saved. Compare the monthly total, not the lease number.
Get at least three written estimates for the same inventory on the same dates, and ask specifically about stairs, elevators, long carries, and packing materials — those are the line items that grow on moving day. If you're renting a truck, price it with mileage, insurance, and the one-way drop fee included, not just the daily rate.
Then write down the costs people forget:
Add another ten to fifteen percent on top. Estimates are estimates, and something always slips.
If you can visit before signing, don't spend the whole trip touring apartments. Drive the commute at the hour you'd actually drive it. Buy a week of groceries at the store you'd actually use. Walk the neighborhood at night and check whether it's quiet, lit, and near the things you do regularly — a pharmacy, a laundromat, a park.
Carry a notebook and record real numbers: the gas price on the corner, what a sandwich costs, what parking runs downtown. Those small figures are exactly what fill the blank spaces in a new budget. If you can't visit, call instead. A property manager, a future coworker, or a local forum can answer one useful question: what's the cost here that surprises new residents?
Do this while you can still say no. Set up three columns:
Then test all three against your income. If fixed costs plus realistic variable spending leave you thinner than you're comfortable with, that's the moment to choose a smaller place or a different neighborhood — not three months after the boxes are unpacked.
Many moves come with a timing gap: you pay a deposit and first month's rent before your old deposit is returned, or before your first new paycheck lands. If you can, keep roughly two months of overlap cash in the bank. If an employer offers relocation help, ask exactly what's covered and when it's paid — reimbursements often arrive weeks after you've already spent the money.
New-city life has its own starter costs: utility connection fees and a high first bill because you're starting from zero, a parking permit, a new driver's license and registration, the vacuum and mop you left behind, curtains for windows that turn out to face west.
Track everything for thirty days — a note on your phone is fine. Then compare actual spending to the plan. Most people find two or three lines that were off, and the fix is usually small: a cheaper phone plan, a different grocery store, one fewer subscription.
If your move is job-related, the rules around what you can deduct have changed in recent years. An hour with a tax professional costs less than guessing.
Move mid-month or midweek if your schedule allows; demand and pricing shift with the calendar. Sell or donate bulky furniture rather than paying to ship it — an old couch that costs real money to move is often cheaper to replace. Pack your own boxes if you're hiring movers for the heavy lifting, and ship books and media instead of hauling them. Ask about flexible-date discounts, and check whether an employer, alumni group, or professional association offers a relocation benefit you've never used.
Give yourself a soft landing. Set the new budget, but leave one modest line for settling in — a plant, a decent lamp, dinner at the neighborhood place — so you don't feel punished by your own spreadsheet. Review the numbers at thirty, sixty, and ninety days and adjust once you know what a normal month actually looks like. If the math doesn't work before you go, waiting a few months and saving more is a better outcome than starting a new city already behind.
Photo: cottonbro studio / Pexels
A practical holiday spending plan: set a realistic total, write a capped gift list, fund it with a sinking fund, and...
A decade-by-decade retirement checklist for your 30s and 40s, covering savings benchmarks, debt payoff order,...
Roth and traditional IRAs both build retirement savings, but the tax timing, income rules, and withdrawal terms...

Personal finance served fresh from the teapot.
